The Financing Process
Demystifying Home Loans
The home loan process can feel overwhelming. By collaborating with a trusted lender and remaining informed through every step of the process, from pre-approval to closing, you can have a significantly more comfortable experience. You’ll want to consult with a mortgage specialist (or two) to find a professional who you are confident will provide you with the best care.
To get an idea of what to expect, review the following home loan process steps.
Step One:
Get Pre-Approval
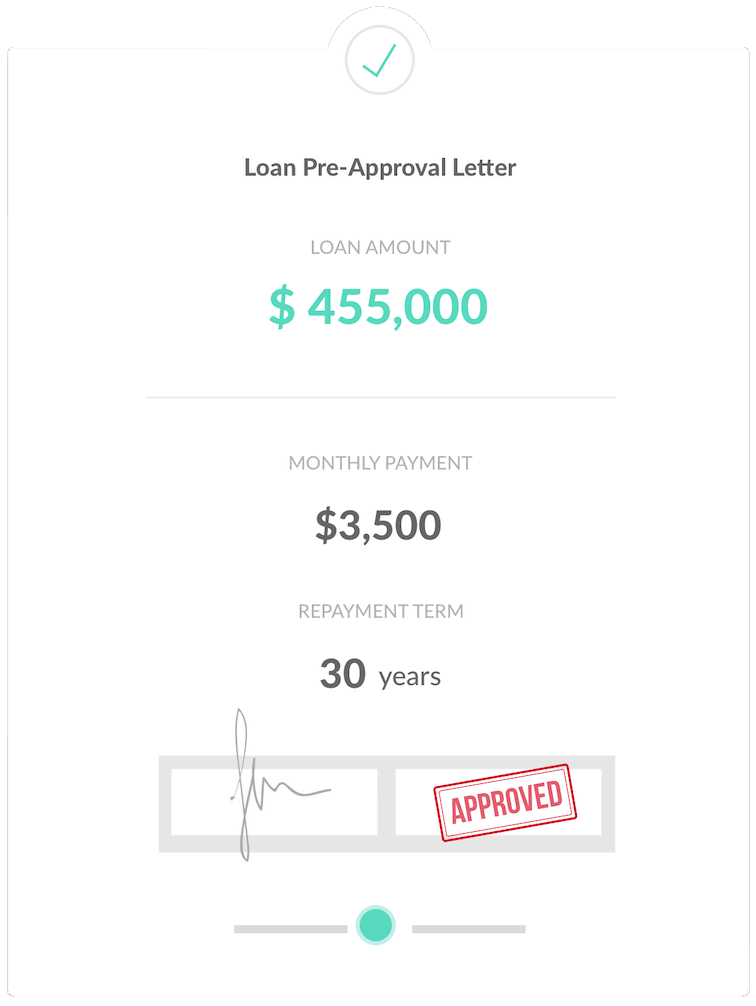
Before you start looking for a home to buy, it’s wise and proactive to meet with a lender to get pre-approved for a loan amount. Offers accompanied by a pre-approval letter are stronger and will stand out, especially when the seller is receiving multiple offers.
To gain pre-approval, your preferred lender will gather information about income, assets, and debts to help determine how much you can borrow. This includes gathering a credit report, W-2 forms, pay stubs, federal tax returns, and recent bank statements.
There are a variety of home loan programs offering different advantages depending on your unique needs and preferences. Your preferred lender can go over the specifics of each to ensure you find a loan option that best aligns with your needs.
Michael Popnoe
Senior Loan Originator
NMLS: 116627 | Licensed in OR, AZ, MT, WA
About Michael Popnoe
Let me tell you a little bit about myself. I’ve been a Mortgage Advisor since 2005 prior to which I was a software engineer. One thing I carried over from the IT world was precision – and I’ve found my mortgage clients have greatly appreciated the level of detail we take when considering their financing options and all the important numbers that come into play. To achieve this in a meaningful way we employ many unique tools – such as our Mortgage Coach Loan Analysis software to educate and empower our clients. Buying or refinancing a home is a major financial endeavor – and I believe in Mortgage Planning – not only at the time of buying or refinancing but for the months and years afterward to manage your home loan and help optimize your wealth.
Outside of work I love to play tennis (poorly) and hit the slopes in the winter. Enjoying unique microbrews and struggling to learn guitar are other hobbies that keep me busy. I look forward to helping you on your journey to homeownership and all of your home loan needs. Contact me today to get started !
Estimate Your Monthly Payment
Estimate your mortgage payment, including the principal and interest, taxes, insurance, HOA, and Private Mortgage Insurance.
Price
Annual Tax
Loan Term (Years)
Down Payment %
Interest Rate %
Monthly HOA
Monthly Insurance
$3,198.20
Estimated Monthly Payment
Principal
$2,398.20
(75.0%)Taxes
$500.00
(15.6%)Private Mortgage Insurance (PMI)
$0.00
(0.0%)HOA
$100.00
(3.1%)Insurance
$200.00
(6.3%)
Step Two:
Find the best loan
Collaborating with a top-notch local loan officer will ensure you have access to competitive rates and programs that best fit your individual needs. Take the first step by completing this form to get connected today!
Step Four:
Signing and finalizing the deal
Once your loan is approved, you’ll need to set up homeowners insurance.
Your documents will be sent to the title company and the closing will be scheduled for you to sign the necessary paperwork and pay any additional costs to complete the purchase of your new home.
After the loan goes through the required recording process, the purchase is complete, and you officially own your new home!